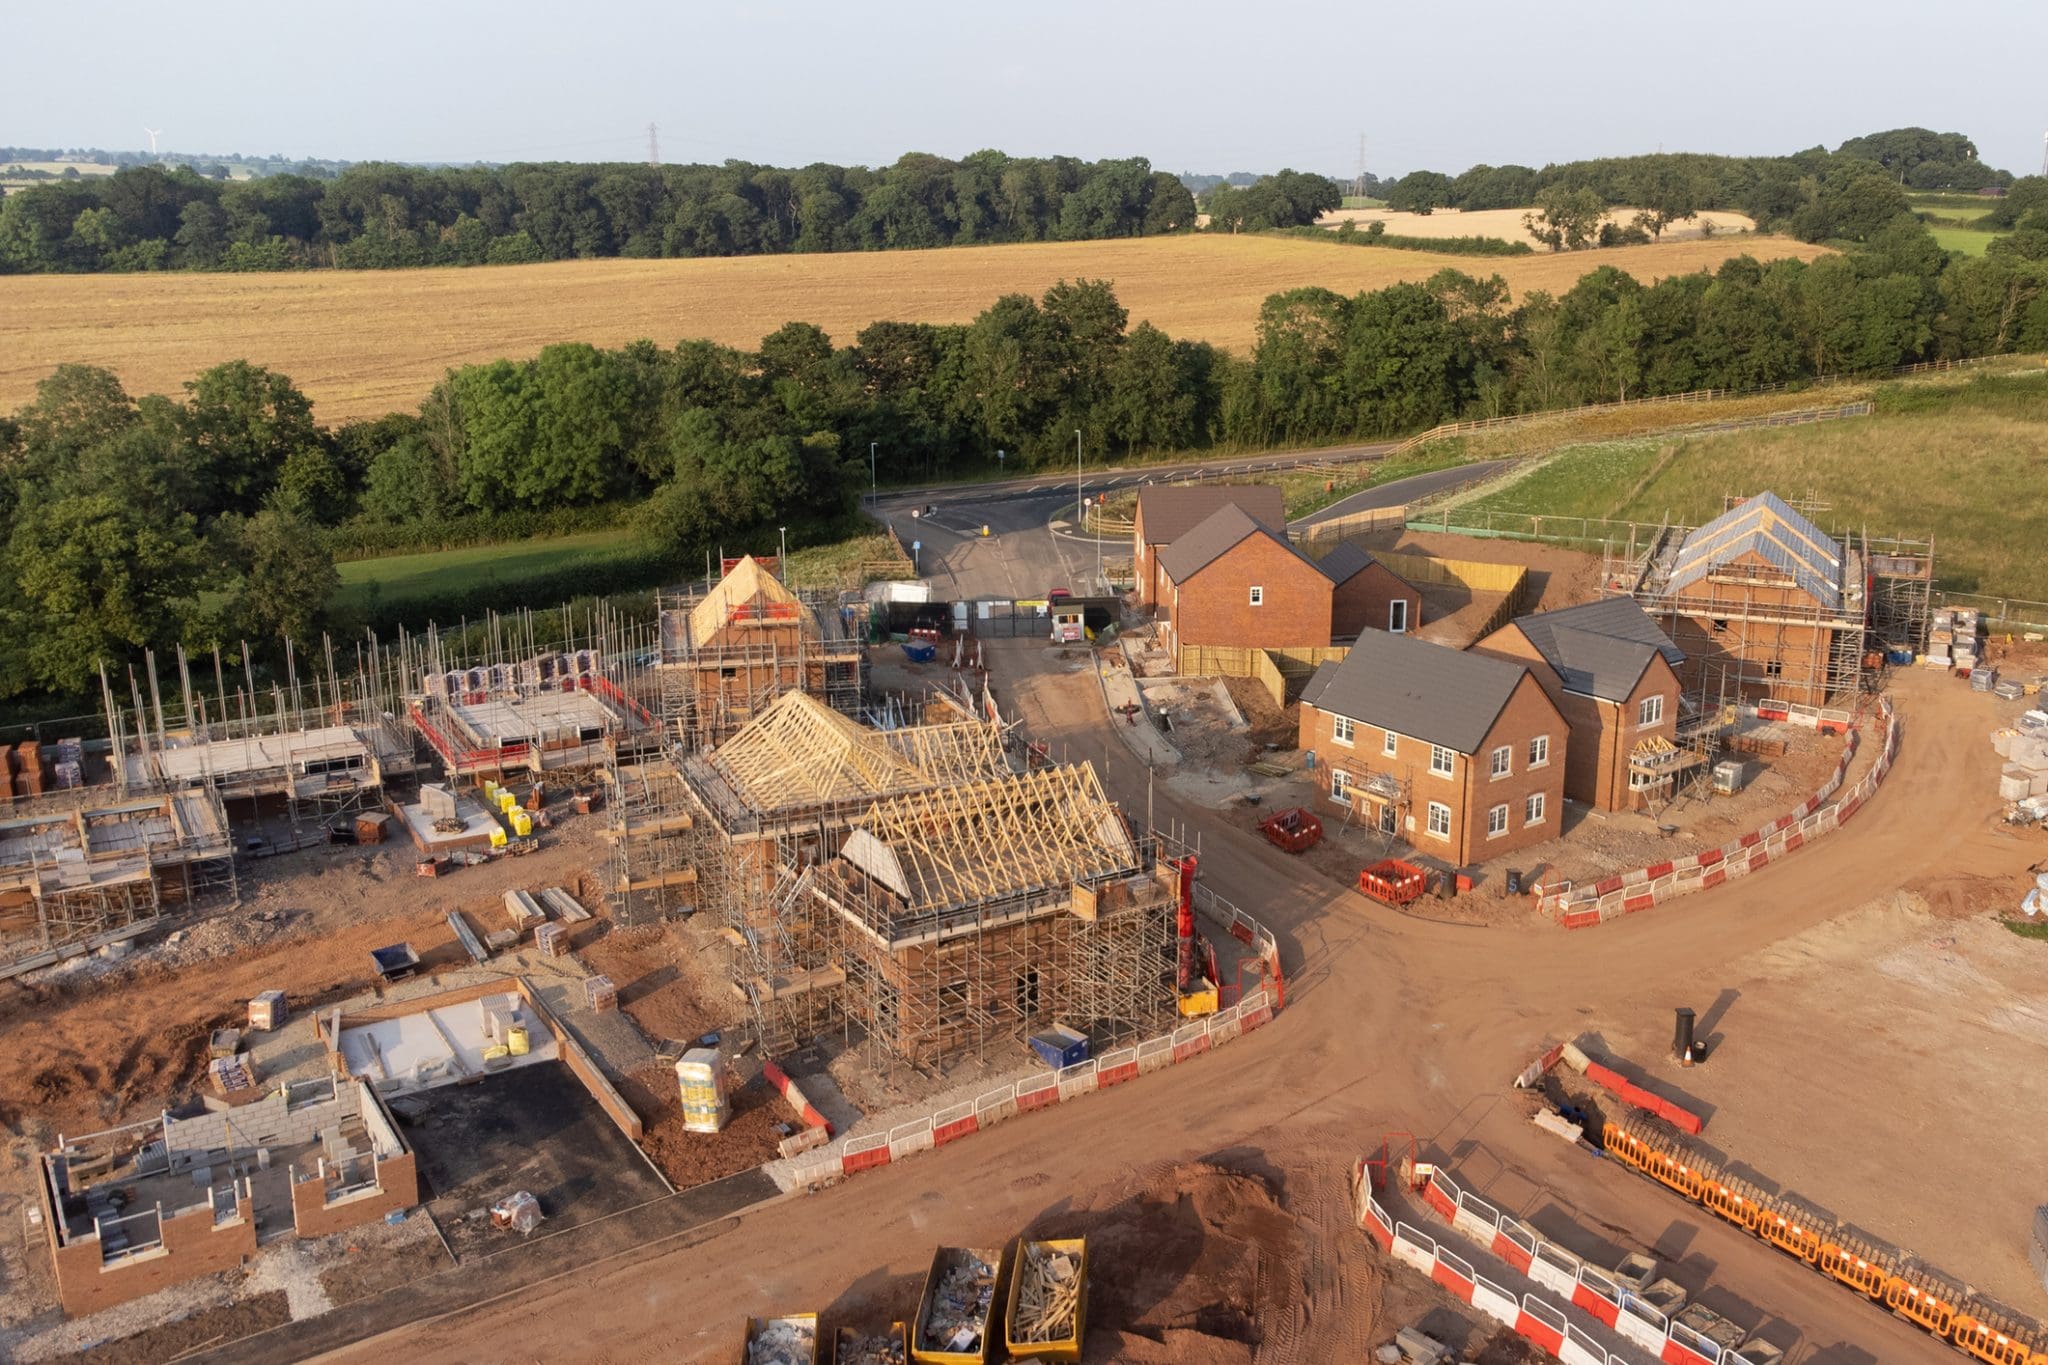
The Your First Home scheme is a new equity loan scheme in England, helping support more people into homeownership
**UPDATE: We have updated the bottom of this article with fresh reactions from industry thought leaders
The new first-time buyer scheme is expected to support 2.5% deposits, with a 20% government-backed equity loan, making it easier for first-time buyers to purchase a property.
The loan will also have an initial interest-free period, saving money for buyers per month compared to other mortgages. Full details will be confirmed as part of the Autumn Budget.
More people buying means more homes built
The deposit is the key barrier to many first-time buyers, and this scheme will help to build it. It will allow buyers to pay 2.5% deposits on new build homes, and the government will cover 20% of the mortgage, leaving a much smaller mortgage for the buyer.
For example, in purchasing a home worth £200,000, the buyer will pay £5,000 in the deposit, the government will loan £40,000, leaving the mortgage to be paid at £155,000.
This scheme will be hailed by some in the industry, as high prices have curbed homebuilding activity. In May last year, the average house price for a first-time buyer rose to £250,000, a rise of 7.7% since the last year, and the average property value in the UK hit £271,000.
This meant that first time buyer prices were just £21,000 cheaper than most houses.
This locked more people out from buying a home, making homes harder to sell, and in turn, meaning fewer profits for housing developers and less funds for the next development, maintain staff, taking on apprentices, etc.
At the time, the chief executive of the National Federation of Builders, said: “First time buyer lending schemes are absolutely vital to buyers and builders, but without a huge increase in supply, there is a risk that buyers overpay for homes. This is why Labour’s commitment to 300,000 homes a year is so important.
“Demand led policies that are unsupported by supply strategies create unintended consequences, such as fuelling house price rises and risking negative equity on certain home types, like apartments, because premiums were paid to get on the housing ladder rather than to purchase the appropriate homes.”
In November last year, Emma Ramell, the director of external affairs at the Home Builders Federation (HBF), wrote for PBC Today to discuss why first-time buyer support would be necessary, writing: “Without a realistic market for new homes, investment in new sites and labour is being limited. To overcome these challenges, the government could provide assistance for first-time buyers at the Budget in the form of a new equity loan scheme part-funded by home builders.
“Not only would this generate positive outcomes for housing supply, home ownership and the wider economy by transforming demand into effective demand for new homes, but it would also give builders the confidence to invest for the long-term.”
Read Emma’s full thoughts on why the scheme will be beneficial here.
“A welcome boost for the industry.”
Of the new first-time buyer scheme, Paul Turner, CEO of the National House Building Council (NHBC), said: “News from Andy Burnham and Angela Rayner of a new equity loan scheme to help first-time buyers purchase new build homes is a welcome boost for the industry.
“The security of owning a high-quality, safe and sustainable home has for too long been out of reach for many hard-working people. It is reassuring that government has recognised this with material support that will help get people on the first rung of the housing ladder.
“But there is no one single solution to the housing challenge. Supply must also be addressed through accelerated planning reform and the easing of unnecessary regulatory burdens. What’s more it’s vital to keep focus on maintaining quality in the construction of new homes.”
Michael Clifford, commercial director at District & County Investments, said: “From a developer’s perspective, anything that helps more first-time buyers overcome the deposit barrier and thus enabling more to buy a new-build home has the potential to support both confidence and housing delivery with developers which should be welcomed.
“One of the challenges developers face at the moment is not necessarily a lack of underlying demand for good-quality housing, but uncertainty around sales rates and how quickly buyers can complete. If this scheme increases the pool of buyers able to purchase a new-build property, that should give developers greater confidence that there will be customers for the homes they are building.
“The details will be important, particularly around the property price caps, eligibility criteria, developer contribution and how quickly the scheme can be implemented. However, there is a clear link between supporting demand and supporting supply and this is a welcome incentive to assist with sales of existing stock, allowing developers to then move to the next project. There are risks associated with this type of assistance, which we have previously seen (i.e., reductions in demand at levels slightly over the max price threshold), but on balance this is very welcome news. If developers have greater confidence that homes will sell, it becomes easier to commit capital to new sites and move schemes forward.”
Phil Hooper, CEO of Close Brothers Property Finance on Your First Home, said: “This is the news the industry has been waiting for. The test now is whether it delivers for SMEs as well as the PLCs.
“Over the past year, an increasing number of SME housebuilders have had capital tied up in unsold stock, holding them back from moving on to new sites and restricting supply. Your First Home should give buyers the confidence boost they have needed, bringing homeownership within easier reach for first-time buyers and helping to free up that capital.
“However, if the scheme is going to make a serious difference to supply, it must work for the housebuilders who need it most. That means developer contributions that are proportionate and terms that SMEs can realistically sign up to. Enabling SMEs to participate at scale will be critical to creating a more diverse and resilient housing market.”
Some experts are cautious
Neil Leitch, managing director of development finance at Hampshire Trust Bank, said: “Across HTB’s development finance book, we are seeing some encouraging signs on the sales side. Monthly sales as a proportion of completed stock are increasing, and we are seeing fewer funded sites go for two months without a sale. Against that backdrop, measures which help first-time buyers overcome the deposit barrier and support home ownership should be welcomed.
“But unless government sorts planning, there is a danger much of this becomes pointless. There is little value in stimulating demand for new homes if developers still cannot get viable schemes through the system in a reasonable and predictable way. The encouraging signs we are seeing on sales do not remove that front-end uncertainty. Planning remains costly, slow and inconsistent, and that is affecting both the number and type of schemes developers are prepared to take forward and where they commit capital.
“The requirement for participating developers to contribute towards the scheme also needs careful thought. Developers already face Section 106, CIL, BNG, significant upfront planning costs and additional requirements associated with building safety. These costs are not experienced in isolation. They accumulate within the same appraisal and directly affect viability. Government cannot keep adding costs to the delivery of the very homes it is trying to help people buy.”
“So yes, help first-time buyers. Buyer incentives matter. But if government wants that support to translate into more homes, it also must fix the supply side. Sort planning, properly resource local planning authorities, make decisions more consistent and predictable and hold the system to account for delivery. Otherwise, we are supporting people’s ability to buy while continuing to constrain developers’ ability to build.”
Simon Gerrard, chairman of Martyn Gerrard Estate Agents, said: “It’s encouraging to see the Government reviving Help to Buy to add stimulus to the market. The housing market has been in desperate need of support and it’s good to see the Government take action to provide it. These schemes are critical to helping hard-working young people who don’t have access to the Bank of Mum and Dad get on the property ladder. They also provide much-needed certainty to developers, which is key to allowing the country to start building homes again.
“However, I’m concerned by the potential implications of some of the announced changes to the scheme. While setting caps on the household income of those using the scheme and the maximum deposit makes sense to ensure it helps those who genuinely need it, this needs to be done carefully to avoid undermining the entire scheme.
“In particular, the scheme needs to consider the local market context. Property values in London are twice the national average, which means people in the capital need a much larger deposit and a higher income than buyers in Northumberland. If the requirements don’t reflect this reality, it could lock out millions of Londoners from being able to access the scheme despite needing support. This scheme needs to be designed for the whole country and not just the North.
“Further, first-time buyers are only one piece of the puzzle, though an important one. For all the recent talk of an autumn bounce, there’s a noticeable lack of ordinary families buying at the moment. Many second-steppers are struggling to move up the ladder, and Help to Buy only helps first-time buyers purchase new-builds, which means they won’t benefit from the increase in first-time-buyer demand.
“The Stamp Duty threshold changes have diminished first-time-buyer purchasing power and the landlord market exodus has caused an imbalance between supply to demand. The Bank of England may have just held rates, but swap rates are still rising. The wider market is in a precarious position. I’m not sure the Government appreciates the housing market’s importance to the wider economy and the seriousness of the current situation. I fear the country faces catastrophe if decisive action isn’t urgently taken.
“Revising Help to Buy is a start, but we need further action in the Autumn Budget to keep the market moving. Raising Stamp Duty thresholds for first-time buyers in more expensive areas would have beneficial effects across the entire market and be far more positive. At the moment, young buyers in the capital are having to save unattainably large sums to get a deposit together to buy.
“Rumours that the Mansion Tax threshold could be lowered to £1.5 million are also unhelpful and would be deeply unwise if market context is ignored. £1.5 million in London could be a two-bed flat. Many ordinary people living in homes they’ve always lived in could face eye-watering tax bills far beyond their means. In effect, local communities face being gentrified out of their areas by their own government.
“Remember, the Mansion Tax threshold doesn’t increase with inflation. Neither does Stamp Duty, while income tax thresholds are being held indefinitely. Together, these measures have a compounding effect, meaning that taxes meant for the wealthy to pay are squeezing an ever-increasing percentage of the population ever harder. These trends are sapping London’s prosperity, and if London falls, the rest of the country will go with it.”